
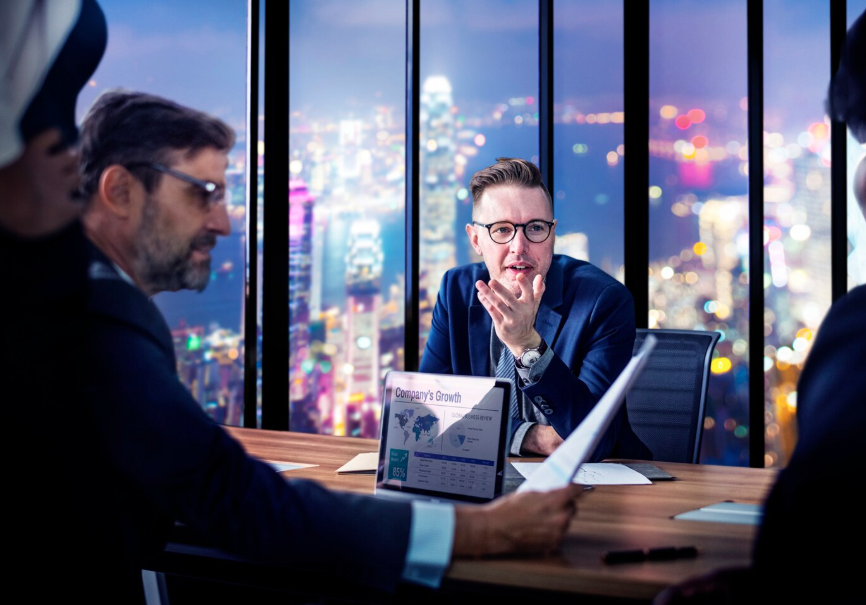
If you run, advise, or invest in a public company, you already know the pressure never really lets up. Earnings deadlines, disclosure rules, audit committee meetings, internal controls, investor expectations. One weak spot in the numbers can turn into a filing delay, a stock drop, or a credibility problem that lingers long after the quarter closes. That is why CPAs for publicly traded companies are not a nice extra. They are part of the structure that keeps the company standing, and even firms associated with Bartlett bookkeeping services can play a supporting role in maintaining financial discipline.
A certified public accountant does more than prepare reports or check boxes. Public companies rely on CPAs to help produce accurate financial statements, support strong controls, reduce reporting risk, and give boards and investors confidence that the numbers can be trusted. When that work is weak, the damage spreads fast. When it is done well, the company moves with more clarity and less avoidable risk.
Public companies depend on CPAs because trust is tied to the numbers
Publicly traded companies live in a world where trust has to be earned over and over. Investors are making decisions based on financial statements. Audit committees are expected to oversee reporting quality. Regulators expect disclosures to be complete and fair. Lenders, analysts, and shareholders all study the same set of numbers, and they notice when something does not line up.
That burden lands on accounting and finance teams first, but it does not stay there. If revenue is recognized incorrectly, if reserves are unsupported, or if internal controls are weak, the issue quickly becomes a governance problem. It can become a legal problem too. A skilled CPA helps prevent that chain reaction by bringing discipline to the reporting process and by challenging assumptions before they become public mistakes.
The Securities and Exchange Commission has made clear that auditors serve investors, not management. The SEC’s overview of the role of auditors explains why independent review matters so much in the public markets. That independence gives financial reporting a layer of credibility that companies cannot create on their own.
Certified public accountants help public companies manage risk before it grows
The hardest problems in public company reporting rarely start as dramatic fraud stories. More often, they begin with pressure, speed, and complexity. A new contract model changes revenue timing. A business acquisition creates valuation issues. A fast close process leaves little room to test assumptions. Someone says, “We will fix it next quarter,” and then next quarter arrives with the same unresolved issue plus a new one.
This is where a CPA for public companies earns their place. A strong CPA sees the weak points early. They ask whether controls actually work in practice, not just on paper. They review estimates with skepticism. They help management document judgments in a way that can withstand audit scrutiny, board review, and regulator attention.
The Public Company Accounting Oversight Board has also stressed the need for meaningful communication between auditors and audit committees. In this PCAOB spotlight on audit committee conversations, the message is plain. Audit quality improves when tough issues are raised clearly and early. CPAs are often the people who surface those issues before they become expensive surprises.
That matters because the cost of getting it wrong is rarely limited to one correction. A restatement can trigger investor lawsuits, regulatory review, added audit fees, financing strain, and damage to leadership credibility. Even if the error was not intentional, the market often treats weak reporting as a sign of weak oversight.
CPAs support governance, compliance, and investor confidence
Public companies do not just need accurate books. They need a reporting system that holds up under scrutiny. That includes quarterly and annual filings, disclosure controls, internal control over financial reporting, and coordination with auditors, counsel, and the audit committee. A certified public accountant helps connect those moving parts.
When finance leaders are stretched thin, it is easy for technical accounting questions to pile up. Lease accounting, stock compensation, impairment testing, segment reporting, tax provision issues. Each one carries judgment calls. Each one can affect disclosures, earnings, and market perception. A CPA brings technical depth, but just as important, they bring process. They help turn accounting from a scramble into a repeatable discipline.
SEC Acting Chief Accountant Paul Munter has spoken directly about the need for high quality audits and professional skepticism in protecting investors. His remarks on audit quality underscore a truth public companies cannot ignore. Reliable reporting is a governance issue, not just an accounting task.
Internal accounting alone versus experienced CPA support
| Area | Internal Team Only | With Experienced CPA Support |
| SEC reporting deadlines | Higher risk of delays when complex issues arise | Stronger planning, documentation, and review process |
| Technical accounting judgments | May rely on limited in house expertise | Better analysis of revenue, leases, equity, and impairment issues |
| Internal controls | Gaps can go unnoticed until audit testing | Weak points identified and addressed earlier |
| Audit committee communication | Issues may be reported late or without context | Clearer escalation of risk, assumptions, and open items |
| Investor confidence | Can be shaken by revisions or inconsistent disclosures | More consistent reporting supports credibility in the market |
The point is not that internal teams are incapable. Many are strong and deeply committed. The problem is capacity and specialization. Public company accounting is unforgiving, and the cost of a gap in judgment is high. Public company CPA services give companies another layer of protection where the stakes are highest.
Three steps that strengthen public company accounting right away
Review your highest risk accounting areas. Start with the areas that depend most on judgment, including revenue recognition, reserves, tax provision, business combinations, and impairment. If support is thin or documentation is inconsistent, fix that first.
Test whether your controls work in real life. A control is not strong because it exists in a memo. It has to operate consistently, leave evidence, and catch errors before they reach a filing. Walk through the process from transaction to disclosure and look for points where people are relying on memory or manual workarounds.
Strengthen communication with auditors and the audit committee. Do not wait for year end to raise difficult issues. Early discussion gives everyone time to assess the accounting, improve support, and avoid last minute conflict. That alone can reduce stress across the finance function.
Public companies are stronger when CPA oversight is built in
You are not overreacting if the reporting burden feels heavy. It is heavy, and public markets do not give much room for preventable mistakes. A certified public accountant helps carry that load by improving accuracy, supporting compliance, and protecting the trust that public companies need to keep. If your company is feeling strain around reporting, controls, or audit readiness, now is the time to bring in the right Certified Public Accountant support.
Read more : Protecting Your Landscaping Business: Key Insurance Considerations/How to Design the Perfect Office Building for Your Business
Related posts:
 The Best Fabrics for Screen Printing: A Guide for Beginners
 Car Defects Demystified: Causes, Consumer Actions, and Lemon Law Legal Assistance
 Strategically Aligning IT Initiatives with Business Goals to Drive Growth
 Expert Legal Support for Real Estate Acquisition and Leasing: Why Freeman Lovell is the Choice for Ambitious Businesses
